Market overview and structural significance of the Automotive Heat Shield Market
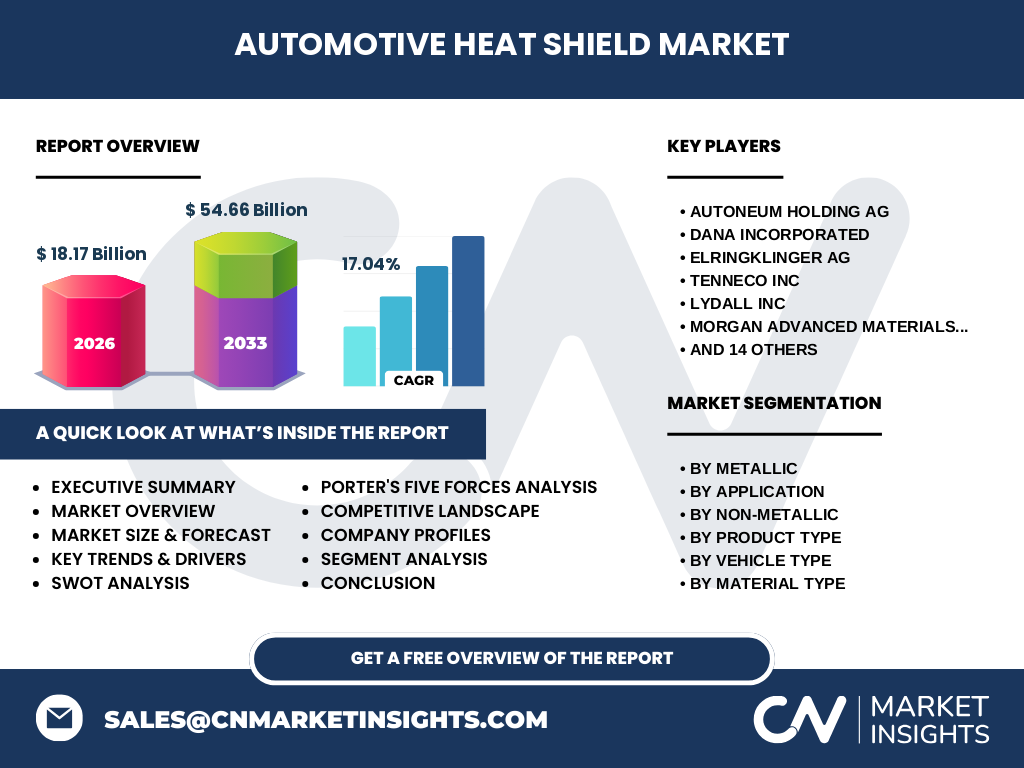
Our analysis indicates that the Automotive Heat Shield Market reached a valuation of 18.17 Billion in 2026. These thermal management systems protect sensitive vehicle components from extreme exhaust temperatures, ensuring regulatory compliance with ISO and SAE standards across global manufacturing hubs.
Structural Growth Drivers and Market Restraints
Stringent emissions regulations by bodies like the EPA and Euro 7 act as major growth drivers, compelling automakers to adopt advanced thermal barriers. However, supply chain volatility in raw aluminum and ceramic fibers creates notable cost pressures for tier-one suppliers.
The Shift Toward Advanced Thermal Management Trends
The industry is experiencing a rapid shift toward lightweight non-metallic solutions to offset heavy EV battery packs. Manufacturers increasingly leverage ceramic and composite shields to enhance under-hood thermal efficiency without adding excess vehicular mass.
Pandemic Recovery and COVID-19 Impact Analysis
Supply chain disruptions during COVID-19 temporarily depressed OE installations, yet post-pandemic recovery has accelerated robustly. The market has rebounded sharply, driven by pent-up consumer demand for modern passenger cars and commercial fleets.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, led by industry innovators like Dana Incorporated and Autoneum Holding AG. These firms secure competitive advantages through proprietary acoustic-thermal insulation technologies and deep-seated OEM supply agreements across North America and Europe.
Executive Summary of the Automotive Heat Shield Market
Our comprehensive research projects the Automotive Heat Shield Market to surge from 18.17 Billion in 2026 to 54.66 Billion by 2033, expanding at a remarkable CAGR of 17.04%. This trajectory underscores the critical role of thermal engineering in modern vehicle architectures.
Long-Term Market Forecast from 2027 to 2033
Driven by the rapid electrification of light and heavy commercial vehicles, the market exhibits exceptional momentum. Our forecasting models confirm the 17.04% CAGR will rapidly expand sector revenues toward the 54.66 Billion threshold by 2033.
Segmentation Analysis across Materials and Applications
The market is categorized by material type into metallic and non-metallic variants, and applications spanning exhaust, turbocharger, and under bonnet shields. Aluminum and stainless steel dominate metallic lines, while fiberglass and ceramics lead non-metallic segments.
Regional Market Distribution and Performance
Geographic performance is heavily anchored by major automotive manufacturing clusters in Asia-Pacific, Europe, and North America. Localized regulatory mandates regarding fuel efficiency heavily influence regional adoption rates of advanced double-shell and sandwich product types.
In-Depth Regional Review of Manufacturing Hubs
Asia-Pacific remains the fastest-growing regional market, propelled by soaring vehicle production in China and Japan. Meanwhile, European markets prioritize stringent Euro-norm compliance, boosting demand for high-performance thermal insulating mats in passenger cars.
Company Profiles and Strategic Positioning
Key players such as ElringKlinger AG, Tenneco Inc, and Morgan Advanced Materials plc focus on lightweighting initiatives. Their strategic positioning emphasizes co-development partnerships with major OEMs to engineer tailored exhaust and under-chassis heat shields.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains moderate to high due to consolidated automotive OEM structures. Meanwhile, threat of substitutes is mitigated by rigorous thermal and structural performance prerequisites mandated by international safety organizations.
SWOT Analysis of the Thermal Management Sector
Strengths lie in advanced metallurgical engineering expertise, whereas weaknesses involve high tooling costs for complex geometries. Opportunities abound in electric vehicle thermal protection, countered by threats from raw material price volatility.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw material extraction of aluminum, silica, and ceramic fibers to tier-one stamping and assembly. Finished shields are supplied directly to OEM assembly plants or distributed through aftermarket channels for replacement needs.
Investment Insights and High-Potential Areas
Investors should target non-metallic composite innovations and EV battery shielding applications. Companies investing in automated stamping and proprietary thermal insulating mats present the highest upside potential during this hyper-growth phase.
Conclusion and Strategic Key Takeaways
The Automotive Heat Shield Market offers lucrative prospects as it scales toward 54.66 Billion. Stakeholders must prioritize lightweighting and compliance with stringent emissions standards to capture long-term market share.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with automotive tier-one executives, and secondary macroeconomic indicators to ensure high analytical fidelity.
Scope of the Report and Coverage Parameters
This report covers global market sizing from 2026 through 2033 across metallic and non-metallic segments, product types, sales channels, and vehicle classes. Limitations include unforeseen geopolitical shifts impacting localized automotive supply chains.
Recent Developments and Industry Innovations
Recent strategic moves feature partnerships between material scientists and automakers to launch ultra-thin composite shields. Firms like Dana Incorporated and Autoneum Holding AG continue to announce capacity expansions tailored for EV thermal integration.